Discount Motorcycle Insurance: How to Lower Premiums Without Losing Claim Protection
Securing discount motorcycle insurance comes down to cutting operational risk…
Securing discount motorcycle insurance comes down to cutting operational risk rather than stripping away your financial recovery in a collision. When adjusters handle motorcycle crashes, the difference between a minor setback and financial ruin is the coverage you kept on your declarations page. By targeting verified safety credentials, structural policy endorsements, and administrative risk reclassifications, you can cut your premium by 10% to 35% without forfeiting vital injury compensation.
| Policy Lever | Average Premium Reduction | Claim-Side Impact & Legal Exposure | Underwriter Verification Required |
| Approved Rider Training | 5% – 15% | None. All policy benefits remain fully active. | Course completion card (e.g., MSF BRC certificate). |
| Multi-Policy Bundling | 10% – 25% | None. May streamline shared property damage claims. | Active auto, homeowners, or renters policy number. |
| Seasonal Layup Endorsement | 15% – 35% (Annualized) | Severe. Operating during layup voids third-party liability and collision. | Written declaration of non-operational storage dates. |
| Higher Collision Deductible | 10% – 20% | Moderate. Increases immediate out-of-pocket payment before insurer pays. | Endorsement change request on declarations page. |
| Anti-Theft Tracking Hardware | 5% – 15% (Comp only) | None. Speeds up total loss recovery and theft payouts. | Purchase receipt, telematics log, or install invoice. |
High-Value Motorcycle Insurance Discounts and How Much They Save
Insurers do not give out rate reductions out of goodwill; they price policies using actuarial risk pools. If you present documented evidence that you are statistically less likely to file a claim, underwriters must adjust your tier.
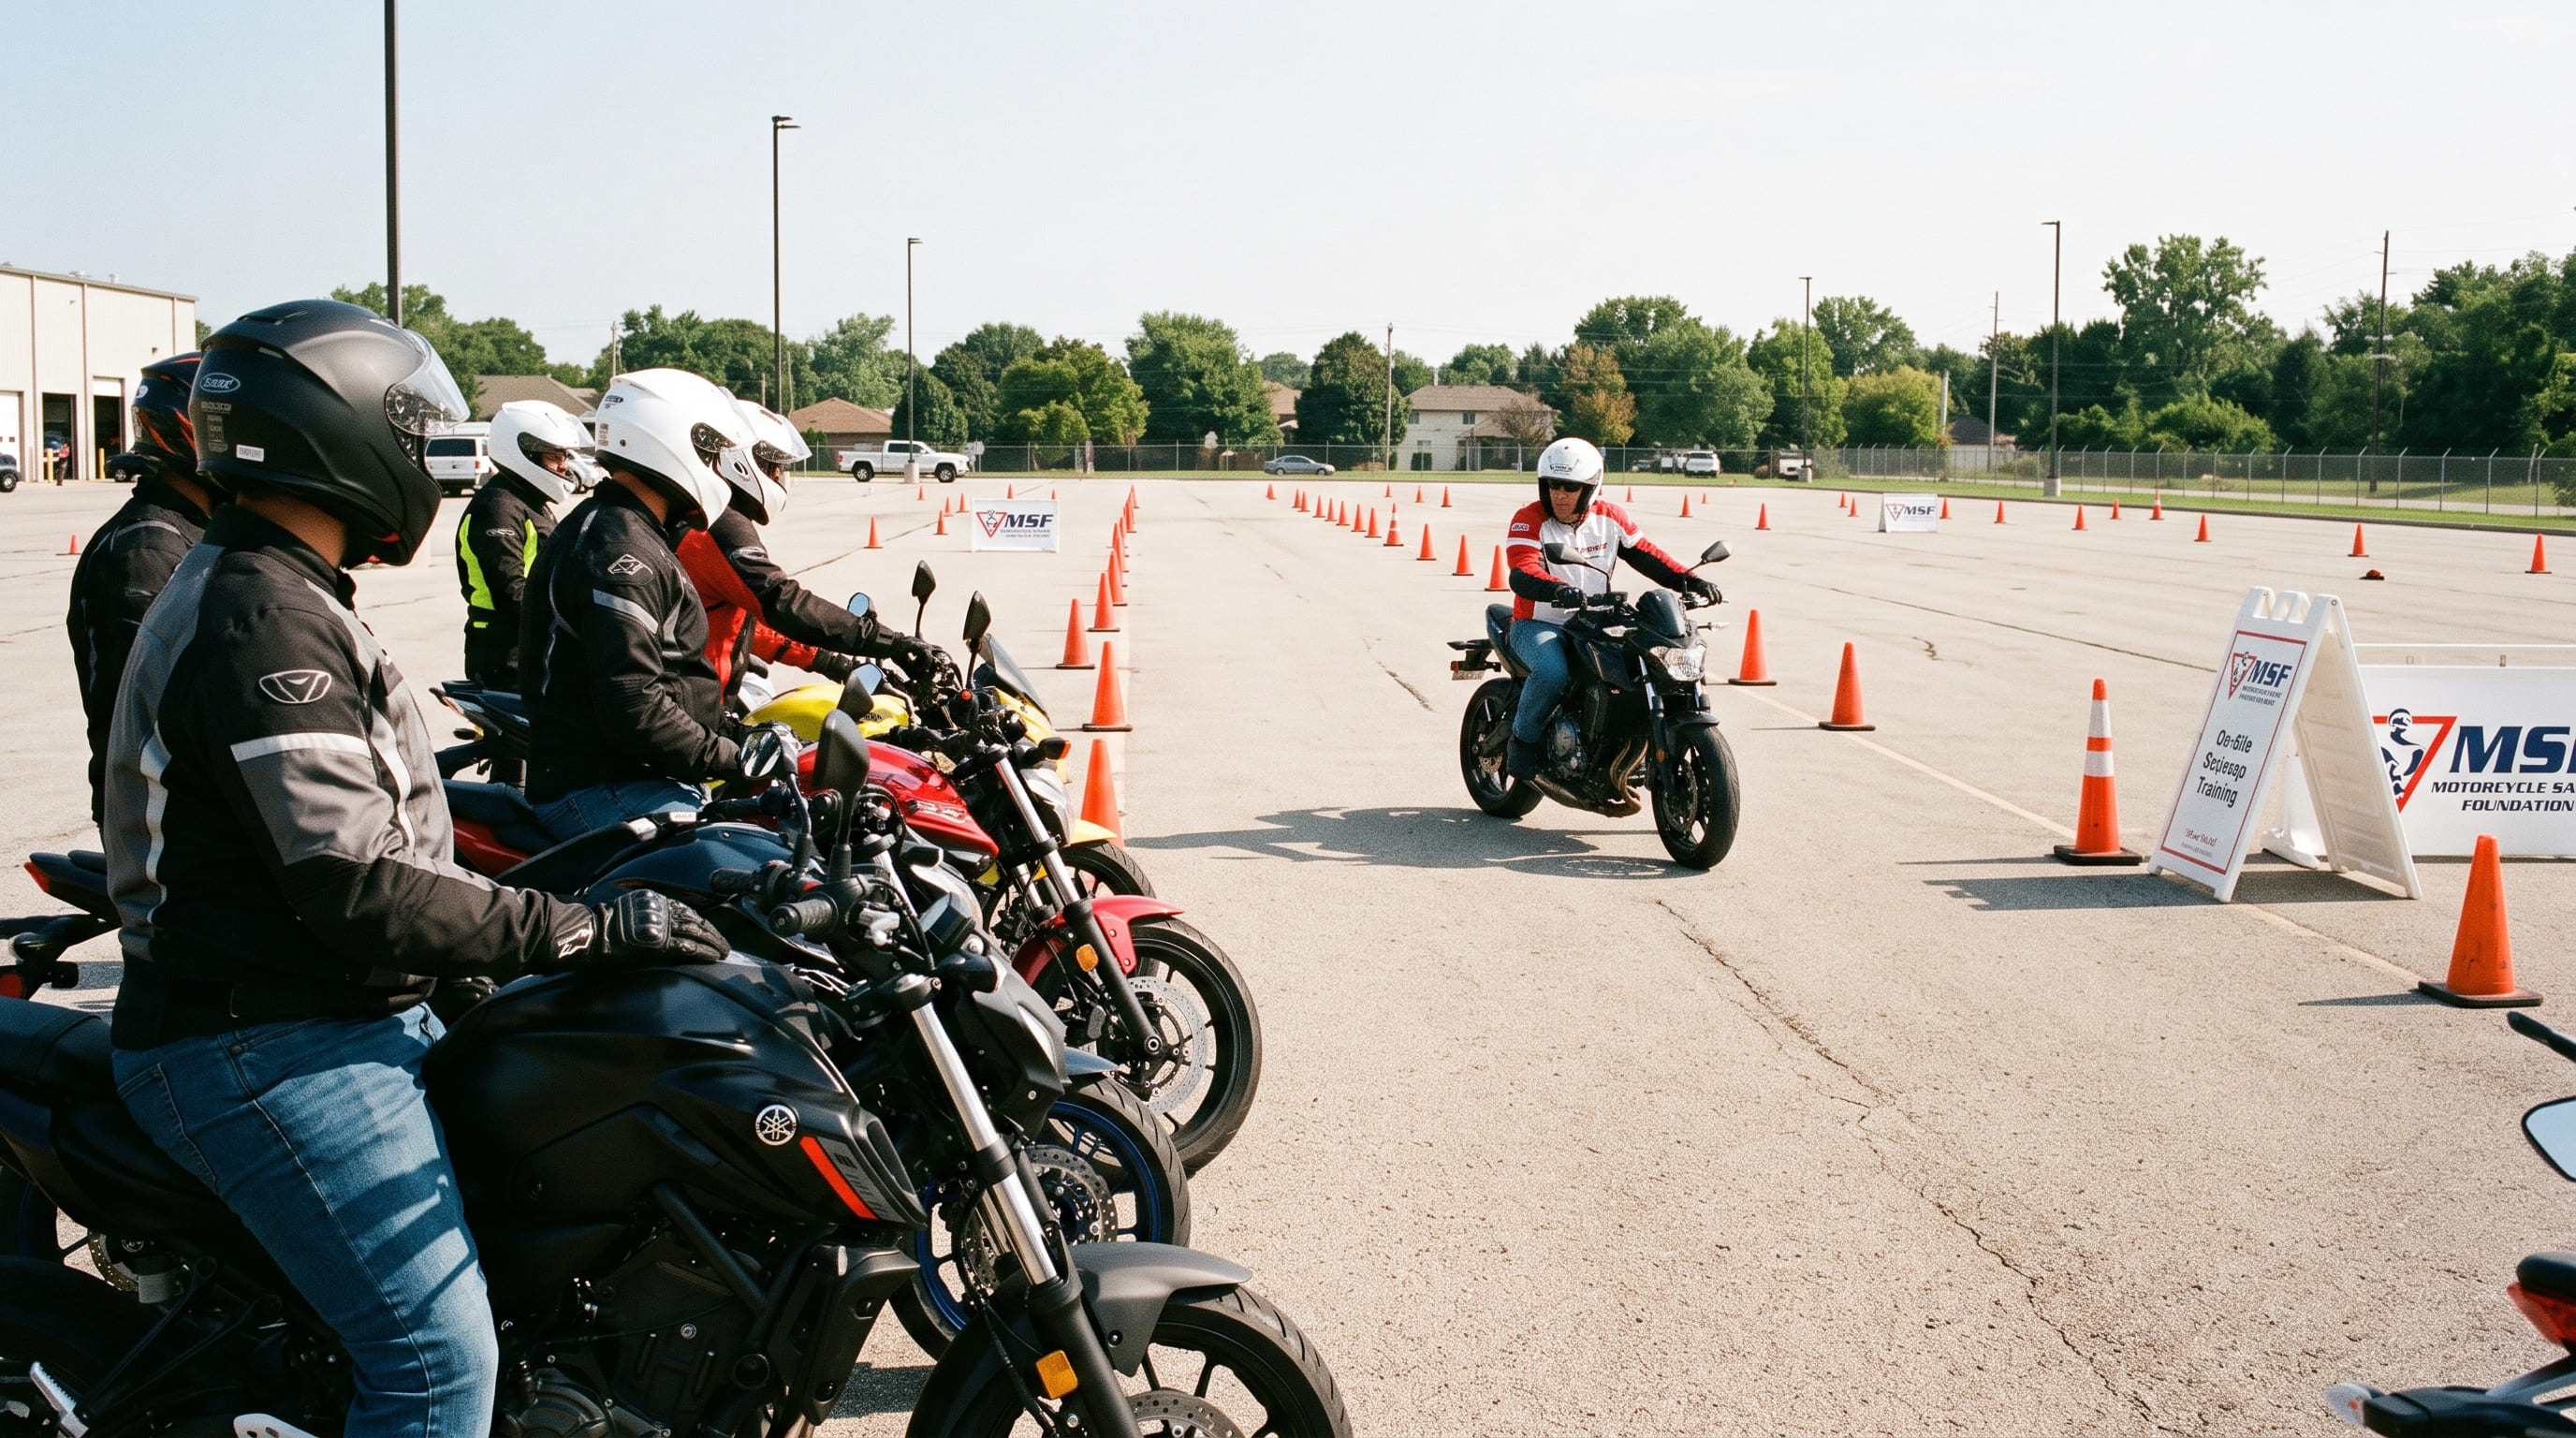
- Rider Training and Safety Endorsements: Completing a course through the Motorcycle Safety Foundation (MSF) or a state-approved program reduces your collision and comprehensive lines by 5% to 15%. Most carriers accept the MSF Basic RiderCourse (BRC) or state-sponsored experienced rider clinics. In states where course completion waives the practical road test at the DMV, carriers frequently grant a multi-year discount tier.
- Multi-Vehicle and Policy Bundling: Stacking your motorcycle with your primary auto or homeowners policy remains the fastest path to discount motorcycle insurance. Combining these accounts yields 10% to 25% in total premium savings. It also simplifies insurer subrogation if an incident damages both your vehicle and your garage.
- Anti-Theft Devices and Garaging: Motorcycles face a higher theft-to-registration ratio than passenger cars. Underwriters credit passive immobilizers, hidden fuel-cutoff switches, and GPS tracking hardware (like LoJack or Monimoto) with a 5% to 15% discount on the comprehensive line. Storing the bike in a locked residential structure rather than on a public street also drops your territorial risk code.
- Affinity and Organization Memberships: Active membership in groups like the American Motorcyclist Association (AMA), the Harley Owners Group (HOG), or branches of the US military unlocks standard 5% to 10% affinity price cuts. Ask your underwriter for their approved group roster.
Seasonal Layup Endorsements: Finding Discount Motorcycle Insurance for Off-Season Months
If you live where winter ice makes riding impossible, paying for full street coverage year-round wastes money. A seasonal layup endorsement lets you lock in discount motorcycle insurance by suspending road coverages while preserving physical protection in storage.
+----------------------------------------------------------------------+
|                     LAYUP POLICY COVERAGE STATUS                     |
+----------------------------------------------------------------------+
|  ACTIVE:     Comprehensive (Theft, Vandalism, Garage Fire, Collapse) |
|  SUSPENDED:  Collision (Impacts, Lay-downs, Pothole Damage)          |
|  SUSPENDED:  Bodily Injury & Property Damage Liability               |
+----------------------------------------------------------------------+
Under a formal layup endorsement, the insurer suspends collision, bodily injury liability, and property damage liability during pre-set calendar months. Your comprehensive coverage stays completely active to cover theft, falling objects, garage fires, or vandalism. This administrative shift lowers your annualized premium by 15% to 35%.
The Legal Trap: You must respect the storage dates. If you take the bike out on a clear winter afternoon during the layup period, you have zero liability or collision coverage. If you cause a crash, your carrier will deny the claim based on the policy exclusion. You become personally liable for all third-party medical expenses and vehicle repairs under your state’s financial responsibility laws.
Before activating a layup plan, confirm your state’s electronic insurance tracking rules. States like California and New York track liability coverage in real time. If an insurer reports that your liability coverage has stopped, the DMV can automatically suspend your vehicle registration and issue fines. To prevent this, file a formal Affidavit of Non-Use or Planned Non-Operation (PNO) with the state DMV before your layup dates take effect.
How to Lower Motorcycle Insurance Rates by Adjusting Coverage Levers
When adjusting policy terms to earn discount motorcycle insurance, you need to weigh short-term premium savings against your actual cash risk during a claim. Changing your coverage levels lowers your bill immediately, but cutting the wrong limits creates massive exposure.
| Policy Adjustment | Baseline Premium Impact | Real-World Financial Risk | Strategic Assessment |
| Raise Deductible to $1,000 | 10% – 20% Reduction | You pay the first $1,000 of repairs before insurer payment starts. | Safe move, provided you keep $1,000 liquid in cash reserves. |
| Audit Custom Equipment (CPE) | 5% – 12% Reduction | Excludes aftermarket pipes, suspension, and fairings from total loss payouts. | Drop if your bike is stock; retain if you have thousands in documented receipts. |
| Remove Insurer Towing | 3% – 5% Reduction | You cover out-of-pocket flatbed towing after a mechanical breakdown. | Drop if you already carry AAA or AMA roadside assistance. |
| Drop Down to State Minimums | 20% – 40% Reduction | Catastrophic. Leaves personal bank accounts and wages vulnerable to court judgments. | Unacceptable risk. Exposes you to personal bankruptcy in any multi-vehicle collision. |
Raising your comprehensive and collision deductibles from $250 or $500 to $1,000 gives you immediate savings. This is an efficient way to capture discount motorcycle insurance, but only if you have that $1,000 set aside in savings. If a hit-and-run driver damages your parked bike, the body shop will not start repairs until your $1,000 deductible is paid.
You should also audit your Custom Parts and Equipment (CPE) endorsements. Most motorcycle policies include an automatic $3,000 CPE limit. If your bike has factory exhaust, stock handlebars, and standard fairings, you are paying an extra charge for equipment you do not own. Removing this surplus rider reduces your baseline cost. Similarly, remove insurer roadside assistance if you already hold emergency towing coverage through an auto club.
Coverages You Should Never Cut for Discount Motorcycle Insurance
Cutting required limits down to statutory minimums to manufacture discount motorcycle insurance creates massive legal liability. If you hit a high-end vehicle or injure someone, standard state minimums will not protect you.
                    THE STATE MINIMUM COVERAGE DEFICIT
+------------------------------------------------------------------------+
|  Typical State Bodily Injury Cap:       $25,000 per person             |
|  Trauma Center & Surgical Costs:        $135,000                       |
|  --------------------------------------------------------------------  |
|  UNCOVERED BALANCE (YOUR DIRECT DEBT):  $110,000                       |
+------------------------------------------------------------------------+
Never reduce these two coverage lines, no matter how small your budget is:
- Bodily Injury Liability: In states with minimum limits like $25,000 per person and $50,000 per accident, a single serious injury will exhaust your coverage within forty-eight hours of hospitalization. Once your insurer pays its maximum policy limit, the injured party’s attorney will target your savings, real estate, and future wages to satisfy the rest of the court judgment. Keep liability limits of at least $100,000/$300,000, and back them with a personal umbrella policy if you own a home.
- Uninsured/Underinsured Motorist (UM/UIM): Motorcyclists take the full physical force of every crash. If an uninsured driver runs a red light and strikes you, their lack of coverage becomes your problem. According to the National Association of Insurance Commissioners (NAIC), uninsured driver rates exceed 15% across numerous jurisdictions. Stripping UM/UIM off your policy to hunt down discount motorcycle insurance leaves your medical bills, lost earnings, and long-term rehabilitation costs completely unprotected. If you are forced to file against your own carrier, follow our structured guide to uninsured motorist claim procedures to protect your payout.
Mitigating Post-Accident Rate Increases and Surcharges
A major collision can raise your rates at renewal, cancelling out any savings you gained from discount motorcycle insurance. Carriers track claim activity through the Comprehensive Loss Underwriting Exchange (CLUE). At-fault claims trigger underwriting surcharges that stay on your record for 36 to 60 months.
               POST-COLLISION UNDERWRITING TIMELINE

 Day 1: Crash Occurs ──> File Initial First-Party or Third-Party Notice
   │
 Weeks 2–4: Adjuster Review ──> Evidence Establishes Liability Proportions
   │
 Month 2: Contested Review ──> Submit Dashcam/Witness Data to Prevent Fault Coding
   │
 Month 3: Policy Renewal ──> Underwriters Pull CLUE Records for Surcharges
   │
 Years 1–3: Surcharge Period ──> Offset Rate Hikes via MSF Retraining & Limit Audits
To prevent or reverse rate increases after an incident, use these claims steps:
- Challenge Inaccurate Liability Apportionment: Underwriters only apply accident surcharges if your adjuster records you as primarily at fault (usually 51% or higher). In pure comparative fault states like California (Cal. Civ. Code § 1714) or modified comparative fault systems like Texas (Tex. Civ. Prac. & Rem. Code § 33.001), liability is divided proportionally. If the other driver made an improper left turn across your lane, supply the police report, intersection camera footage, and witness accounts to dispute unfair fault claims. Learn more about protecting your record in our detailed guide on comparative negligence in motorcycle accidents.
- Correct Fault Codes on Your CLUE File: If an accident was caused entirely by another party and your insurer recovered its costs through subrogation, confirm that your carrier codes the claim as “not-at-fault.” Administrative errors often leave claims marked as chargeable losses, which causes other insurers to quote higher rates when you shop for discount motorcycle insurance.
- Compare Repair Costs to Claims-Free Discounts: If you drop your bike at low speed and scratch a fairing or mirror, pay for the parts yourself if the bill is near your deductible. If repairs cost $800 on a $500 deductible, filing a claim nets you only $300. In return, you lose a 10% to 15% claims-free discount for three years, which will cost you far more than that $300 payout. If structural or frame damage totals the machine, review our guide on motorcycle total loss and GAP coverage before you accept the insurer’s initial settlement offer.
Frequently Asked Questions
Can I get discount motorcycle insurance if I have a speeding ticket on my record?
Yes, but you will need to actively offset the points added to your Motor Vehicle Record (MVR). Moving violations generally trigger underwriting surcharges for three full years. You can balance out these surcharges by completing an advanced MSF course or an approved defensive driving class, which many carriers accept for immediate policy discounts. If your primary insurer issues a steep rate increase, look for quotes from carriers that specialize in non-standard motorcycle risk.
Will keeping comprehensive-only coverage during winter suspend my license?
In states with electronic insurance reporting, dropping your liability coverage without notifying the motor vehicle agency can trigger an immediate registration suspension. If the state detects a lapse in mandatory liability coverage, it may mail you a notice of intent to suspend. To prevent this, submit a formal Affidavit of Non-Use or Planned Non-Operation (PNO) document to your state DMV before you suspend road liability coverages through a winter layup endorsement.
Does my credit score affect my ability to find discount motorcycle insurance?
In most states, insurance companies use credit-based insurance scores to calculate underwriting risk tiers. Actuarial data shows a correlation between credit history and claim frequency, meaning a lower score can increase your baseline premium. If you live in states like California, Massachusetts, or Michigan, state insurance regulations restrict or prohibit using credit scores to set auto and motorcycle rates. In all other states, improving your credit rating remains an effective long-term method for reducing policy costs.
How often should I reshop my policy to secure discount motorcycle insurance?
You should re-quote your motorcycle coverage once every twelve months, or immediately whenever your driving record clears an old ticket or accident. Insurance companies routinely update their underwriting models, risk territories, and base rates. A company that penalized you two years ago for a minor ticket may offer the most competitive discount motorcycle insurance in your zip code today.
Your Actionable Policy Audit: Next Steps
Do not wait for your policy renewal notice to arrive to start lowering your rates. You can audit your coverage and request policy changes at any time:
- Review Your Declarations Page: Read through your itemized endorsements. Remove coverage you do not need, such as custom equipment riders on a stock bike, passenger liability if you ride with a rear seat cowl, or duplicate towing services.
- Submit Your Proof to Your Carrier: Contact your agent with your documents ready. Send in your MSF course card, proof of membership in qualifying rider associations, and documentation of installed GPS or anti-theft hardware.
- Shop Competing Carriers Using Identical Limits: Request quotes from at least three competing specialty motorcycle insurers using the exact same liability, deductible, and UM/UIM limits. This isolates the base rate differences so you can find the best pricing without losing coverage.
- Check Regulatory Complaint Ratios: Before switching carriers to secure discount motorcycle insurance, review their consumer complaint index on the National Association of Insurance Commissioners (NAIC) Consumer Insurance Search portal. Low premiums mean very little if the carrier routinely stalls or disputes valid collision claims.