How Long Do I Have to File an Insurance Claim When Fault Is Disputed?
How Long Do I Have to File an Insurance Claim…
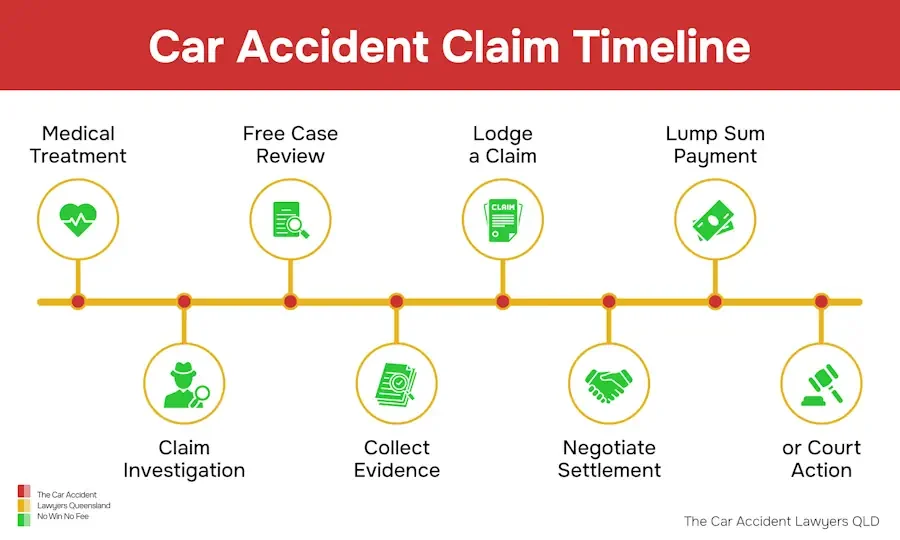
Table of Contents
How Long Do I Have to File an Insurance Claim When Fault Is Disputed?
Review our detailed guide on comparative fault rules by state to calculate how partial liability impacts your final payout.
The answer depends on two separate deadlines: your policy’s private contract terms and your state’s civil statutes. Standard auto policies require you to report a collision “promptly” (typically within 24 to 72 hours), while state laws grant between 1 and 6 years to take formal legal action.
In states enforcing modified comparative negligence (51% bar rule), such as Texas (Tex. Civ. Prac. & Rem. Code § 33.001) or Illinois (735 ILCS 5/2-1116), you are barred from all recovery if your proportion of fault reaches 51% or greater. If your fault is 50% or less, your recovery is reduced proportionately.
In pure comparative negligence states (e.g., California), you may recover damages even if you are 99% at fault, though your payout is reduced by your fault percentage. Prompt filing triggers black box (Event Data Recorder) downloads, scene mapping, and component testing before vehicles are scrapped or repaired.
Property Damage: Actual Cash Value vs. Belongings
Auto policies settle vehicle total losses on an Actual Cash Value (ACV) basis: replacement cost minus physical depreciation and prior damage.
- Uninsured Motorist Property Damage (UMPD): In hit-and-run incidents where the adverse driver is unidentified, state laws frequently cap UMPD recovery (e.g., California sets a $3,500 statutory cap under Cal. Ins. Code § 11580.26) and require an official police report within 24 hours as a strict condition precedent to coverage.
- Personal Belongings: First-party collision coverage strictly covers factory and permanently attached equipment. Damaged personal property inside the vehicle—including phones, child safety seats, and laptops—must be claimed against the at-fault driver’s property damage liability coverage or filed under your homeowners/renters policy.
Insurer Settlement Deadlines (NAIC Standards)
State regulations restrict how long adjusters can delay claims investigations. The National Association of Insurance Commissioners (NAIC) Model Unfair Property/Casualty Claims Settlement Practices Regulation (#902) establishes baseline procedural targets:
- Claim Acknowledgment: Insurers must acknowledge the initial report and supply claims paperwork within 15 calendar days.
- Investigation and Liability Decision: Carriers have 15 to 30 days following receipt of completed proof of loss to approve or deny the claim.
- Payment Remittance: Following written settlement agreement, payments must typically clear within 5 to 10 business days.
- Mandatory Status Letters: If an insurer cannot conclude an investigation within statutory timelines, it must issue written notifications every 30 to 45 days detailing the explicit legal and factual grounds requiring extension.
Step-by-Step Protective Filing Protocol
Opening a claim does not require settled repair bills or finalized medical records. Initiating a protective claim preserves contract compliance under ISO Form PP 00 01 while shielding your claim from third-party bad faith or driver abandonment.
- Submit Concrete Facts Only: Provide the exact loss date, time, physical intersection, vehicle identifiers, and the responding police department agency incident number.
- Withhold Unqualified Medical Assertions: Avoid early statements such as “I am uninjured.” Latent cervical spine trauma, soft-tissue strains, and post-concussive syndromes may manifest 48 to 72 hours post-impact. State: “I am monitoring for physical symptoms and evaluating them with medical providers.”
- Refuse Adverse Recorded Statements: You are contractually required to cooperate with your own insurer. You are under no legal obligation under general tort rules to provide recorded interviews to third-party adjusters without representation. Refer to statutory tort standards via the Cornell Law School Legal Information Institute prior to discussing contested liability.
Frequently Asked Questions
What happens if the other driver promises to pay out of pocket, then disappears?
File a first-party collision claim immediately. Your insurer will investigate under your policy, provided your reporting delay has not prejudiced their ability to inspect vehicle damage or establish subrogation targets.
Does filing an initial insurance claim automatically raise my rates?
In several states, statutes strictly prohibit premium surcharges for non-fault claims (e.g., California under Proposition 103, Cal. Ins. Code § 1861.02; Oklahoma under 36 Okla. Stat. § 941). Filing a zero-dollar protective notice minimizes non-disclosure risks during future underwriting audits.
What is the deadline to file an Uninsured Motorist (UM) claim?
UM claims are contractual actions against your own carrier. While policy provisions govern initial notice, appellate case law uniformly establishes that insurers cannot enforce a legal limitations window shorter than your state’s underlying personal injury statute of limitations.